The economic landscape of American home-front mobilization changed fundamentally on October 3, 1917, when Congress enacted the War Revenue Act. Passed six months after the United States declared war on Germany, the sweeping measure sought to raise vast new federal revenue for the nation’s expanding military commitment, including the training, equipping, and deployment of the American Expeditionary Forces.
Recognizing that customs duties and other traditional revenue sources could not finance modern industrial war, Congress greatly expanded the reach of the federal income tax. The Act reduced personal exemptions to $1,000 for single taxpayers and $2,000 for married couples, with an additional $200 exemption per child. That substantially broadened the income-tax base.
The law also raised corporate taxes, imposed major levies on excess business profits, and sharply increased individual surtaxes. For the highest earners, the Act’s normal income taxes and surtax together produced a top marginal rate of 67 percent on annual income above $2 million.
The law reflected a broader wartime belief that personal wealth and exceptional corporate gains should contribute to national defense. Its excess-profits tax applied to profits above a defined normal return on invested capital, making it one of the Act’s most consequential—and controversial—provisions. The 1917 law imposed graduated excess-profits-tax rates ranging from 20 to 60 percent.
The War Revenue Act did not finance the war by itself. Borrowing, especially through Liberty Loan bond campaigns, supplied the largest share of U.S. war finance; one major estimate attributes 58 percent of war financing to public borrowing, 22 percent to taxes, and 20 percent to money creation. More than a stand-alone revenue measure, the Act marked a major step toward the modern federal approach to national emergencies: a tax-and-borrow system through which Washington could mobilize far larger sums from personal incomes, corporate profits, and public credit.
Its exact rates and structure did not last unchanged. Congress substantially revised wartime taxation in the Revenue Act of 1918. What endured was the enlarged federal fiscal role and the income tax’s greater importance in federal finance: internal revenues, largely income and excise taxes, rose to 72 percent of total federal revenue in 1917 and 88 percent in 1918.
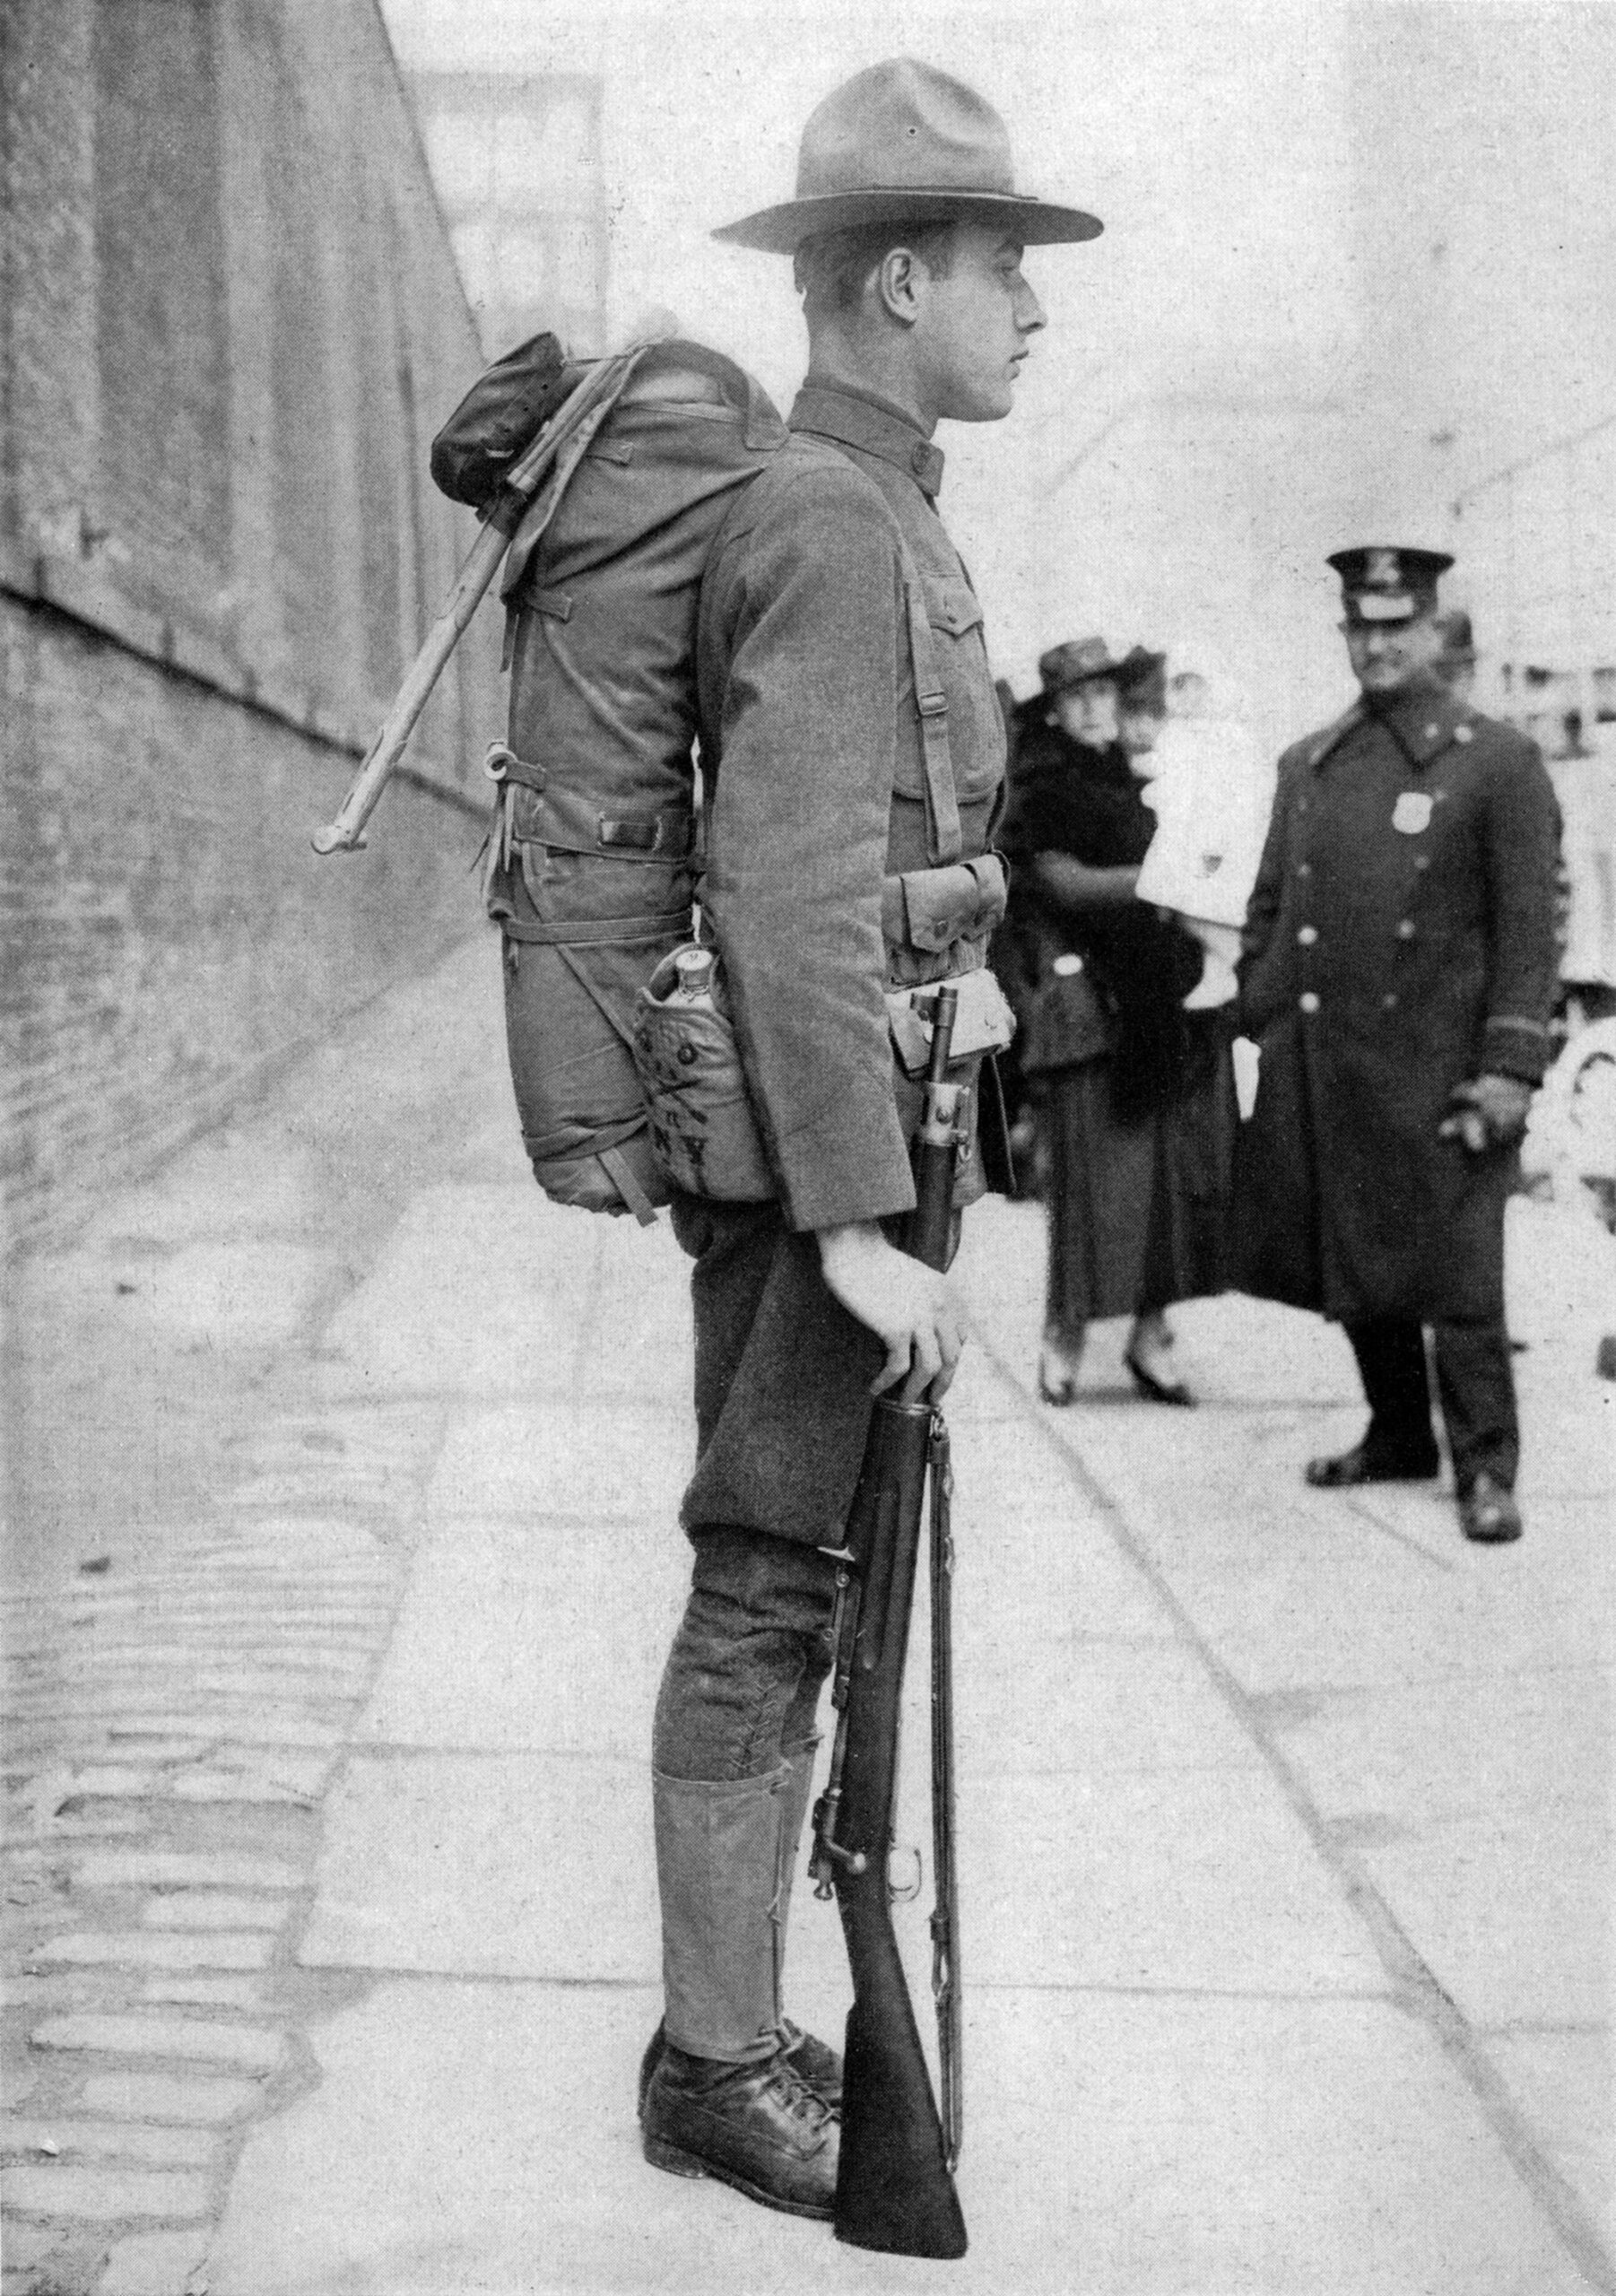
Image credit: “On his back this American fighting man carries his blanket roll, small shovel, hat, etc. His canteen is at his belt. He is armed with a .30 caliber U.S. Army rifle,” via Wikimedia Commons, public domain.